Krungthai Card Public Company Limited (SET: KTC) is entering 2027 with a clear priority: protecting asset quality while pursuing measured growth, as Thailand’s consumer finance sector continues to face pressure from elevated household debt, fragile consumer confidence, and intense market competition.
Speaking during the company’s third-quarter 2026 earnings call, Chief Executive Officer Pittaya Vorapanyasakul said “KTC remains committed to a disciplined growth strategy centered on portfolio quality, prudent risk management, and long-term profitability rather than aggressive expansion. We continue to see an operating environment shaped by high household debt and uneven spending recovery. In this environment, maintaining asset quality and growing with the right customers are more important than pursuing growth for its own sake.”
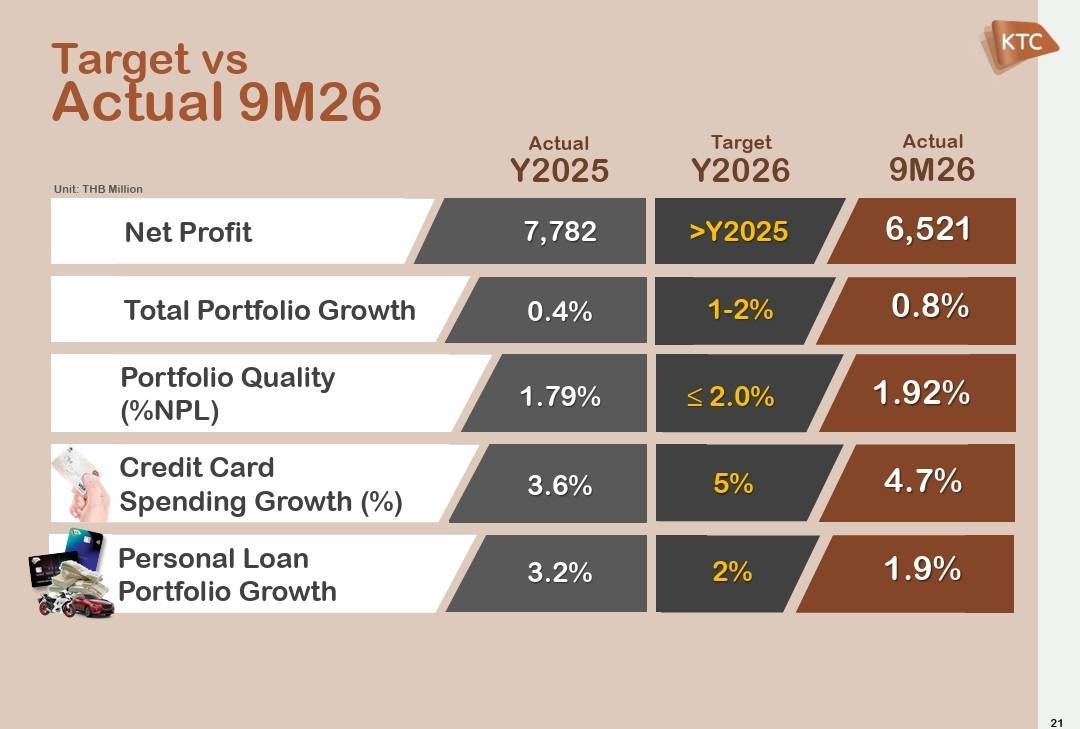
“The strategy has enabled KTC to outperform the broader market. During the first nine months of 2026, spending on KTC credit cards increased 4.7% year-on-year, compared with industry growth of 3.0%, reflecting the company’s ability to sustain spending momentum amid cautious consumer sentiment.”
As of Sept. 30, 2026, KTC maintained a 14.5% share of Thailand’s credit card receivables market, unchanged from a year earlier, while its share of the personal loan market stood at 4.2%.
Asset quality remains one of the company’s key strengths. KTC reported a non-performing loan (NPL) ratio of 1.92%, remaining comfortably below its internal threshold of 2%. The company also maintained an NPL coverage ratio of 413.4%, underscoring its conservative provisioning approach and readiness to navigate potential economic volatility.
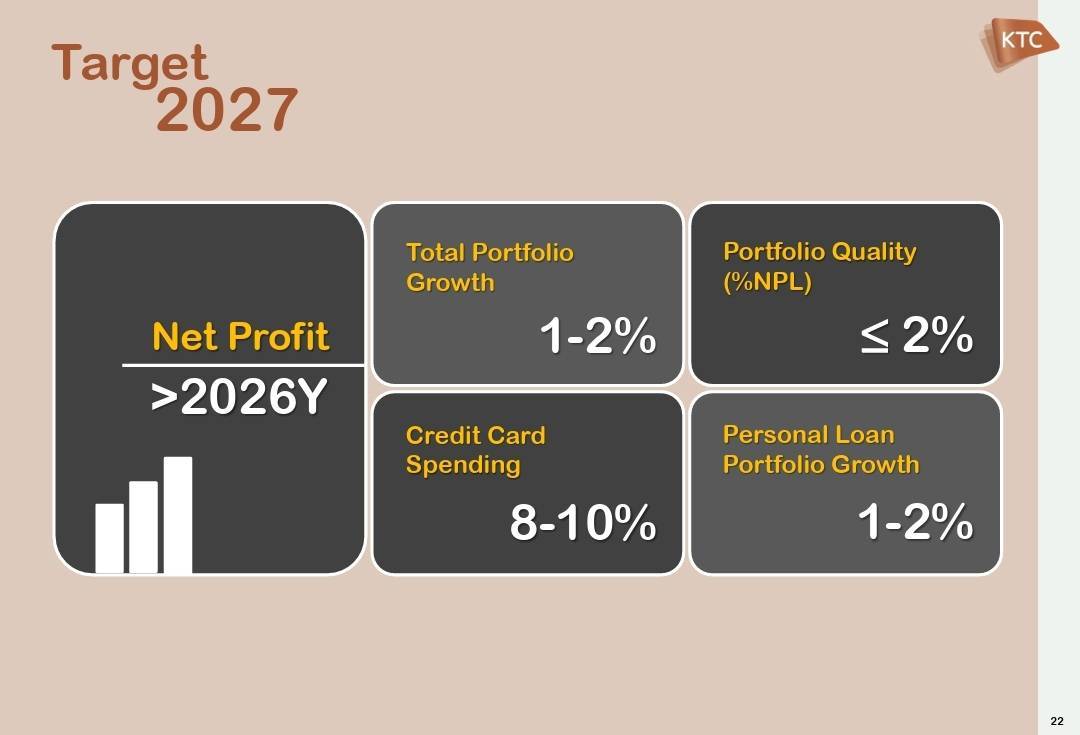
“Looking ahead, KTC expects credit card spending to grow between 8% and 10% in 2027, supported by targeted customer acquisition, stronger member engagement and the use of data analytics to deliver more relevant products and benefits. Total loans and personal loans are projected to grow by 1% to 2%, while the company aims to keep NPL below 2%.”
“The company is also increasing investment in digital capabilities and cybersecurity as it seeks to enhance operational efficiency, strengthen risk management and improve customer experience across its platforms.”
Beyond its core lending business, KTC sees additional growth opportunities in insurance brokerage. The company plans to expand both online and offline distribution channels and is currently seeking approval to offer insurance products through electronic platforms, enabling broader customer access and supporting future fee-based income growth.
Separately, KTC is taking part in a restructuring initiative within the Krungthai Bank financial group aimed at improving operational efficiency, debt management capabilities, and cost effectiveness.
As part of the initiative, KTC acquired shares in Win Performance Co., Ltd. (WIN), a long-standing debt collection partner, in August 2026. In October, KTC transferred its holdings in WIN and KTB Leasing Co., Ltd. (KTBL) to Krungthai Allianz Holding Co., Ltd. (KTAH). Following the transaction, KTC and KTAH each hold a 50% stake in both companies. On Nov. 5, 2026, shareholders of WIN and KTBL approved a merger, marking another step in the financial group’s effort to streamline operations and strengthen collaboration across its businesses.
KTC currently serves 3.87 million member accounts, including 3.16 million credit card accounts and 710,442 personal loan accounts. The scale of its member base, combined with a strong balance sheet and disciplined risk management, provides a foundation for sustainable growth as the company navigates an evolving consumer finance landscape.
“Quality remains the cornerstone of our growth strategy. By maintaining financial discipline while investing in future capabilities, we believe KTC is well positioned to deliver sustainable growth and long-term value for all stakeholders,” Pittaya said.