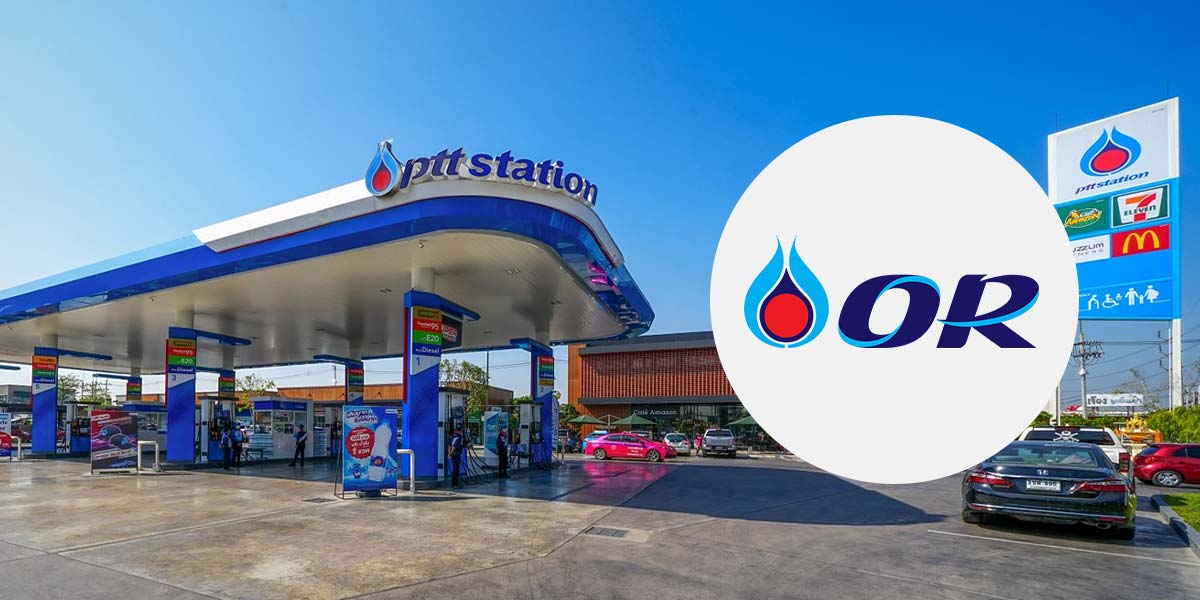
Finansia Syrus Securities has published an analysis on PTT Oil and Retail Business Public Company Limited (SET: OR), forecasting third-quarter 2026 net profit at THB 5.0 billion, reaching a more than two-year high and marking a turnaround from a net loss of THB 1.8 billion in 2Q26.
The recovery is primarily driven by a rebound in the Mobility business following higher global crude oil prices, enabling the company to reverse an estimated THB 2.4 billion net realizable value (NRV) inventory loss recorded in the previous quarter.
Excluding the positive impact of the NRV loss reversal, OR’s core profit is estimated at approximately THB 2.6 billion, representing a 277.7% quarter-on-quarter surge and a 7.3% year-on-year increase, reflecting a recovery in core operations. The performance was supported particularly by the oil distribution business benefiting from rising global crude prices, while revenue from Café Amazon remained consistently strong.
In the Mobility segment, 3Q26 oil sales volume is projected at 5,593 million liters, flat QoQ despite entering the rainy season, which typically exerts downward pressure on travel demand. Retail market oil sales volume is estimated to drop about 3% QoQ, whereas commercial market sales volume is expected to rise 4% following price reductions aimed at enhancing competitiveness.
On a YoY basis, oil sales volume is expected to decline as elevated fuel prices constrain consumer travel. The average selling price is projected to decrease QoQ but increase YoY in line with global oil price movements, resulting in Mobility revenue falling 16.4% QoQ but rising 11.8% YoY.
Meanwhile, the marketing margin for oil is expected to recover to THB 1.20 per liter, supported by inventory gains driven by rising oil prices, serving as a key factor sustaining Mobility segment profitability during the quarter.
In the Lifestyle segment, particularly Café Amazon, operational performance is expected to remain solid. Although sales were affected by the “Thai Chuay Thai Plus” scheme, promotional activities helped mitigate the impact, with 3Q26 beverage sales volume estimated at approximately 116 million cups, down slightly from 117 million cups in the prior quarter.
At the same time, the continuous branch expansion of Café Amazon and 7-Eleven convenience stores continues to support Lifestyle revenue. The analysis estimates Lifestyle segment revenue at THB 6.5 million, up 0.6% QoQ and 9.1% YoY.
The Lifestyle business EBITDA margin is projected at 30.4%, down slightly from 30.8% in 2Q26, but up from 28.2% in 3Q25, demonstrating an ability to preserve profit margins amid competition and purchasing power headwinds.
Looking ahead to the remainder of 2026, Finansia expects OR’s core profit to continue recovering in the fourth quarter. However, the brokerage revised down its core profit forecasts for 2026 – 2028 by 9.0%, 12.4%, and 11.7%, respectively, following reductions in assumptions for oil sales volume, Lifestyle revenue, and share of profit from investments.
Following these revisions, 2026 core profit is projected at THB 10.6 billion (up 3.4% YoY), while 2027 core profit is expected to remain flat, indicating limited growth potential in core operations despite long-term upside potential from non-oil expansion.
Finansia maintains a “Buy” rating on OR while updating its target price to THB 15.00 per share for 2027, based on a sum-of-the-parts (SOTP) valuation. The brokerage noted that despite constrained earnings growth, OR offers an attractive expected annual dividend yield of approximately 4% alongside non-oil growth opportunities, while valuation remains low with 2027 EV/EBITDA trading at roughly 6.1 times, or 1.3 standard deviations below its long-term average.