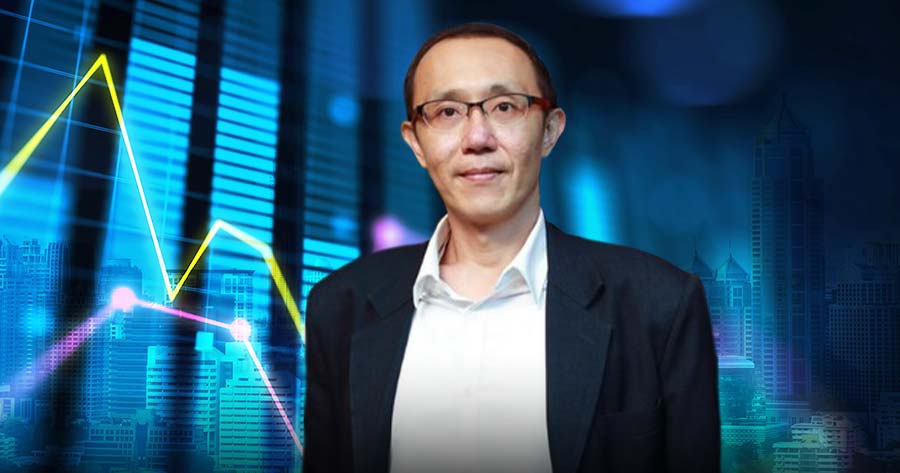
Mr. Chaiyot Jiwangkul, Assistant Director of Securities Analysis at Krungsri Securities (KSS), during the “Kaohoon” program on September 23, 2026, stated that the short-term trajectory of the Thai stock market is likely entering a consolidation phase while investors await clarity on major international developments.
Global markets are focused primarily on tensions between the United States and Iran, as well as the upcoming bilateral summit between the U.S. President Donald Trump and Chinese President Xi Jinping.
Regarding the U.S.-China summit scheduled for September 24, 2026, market participants are concentrating heavily on trade, artificial intelligence, critical minerals, and supply chains—issues with significant implications for global technology sectors and investment trends. The meeting between the two leaders is being monitored closely worldwide this week.
Mr. Chaiyot noted that recent rallies in overseas equity markets were driven predominantly by technology and AI-related stocks. Meanwhile, with broader markets adopting a wait-and-see approach ahead of the U.S.-China discussions, short-term market movements are unlikely to feature broad-based buying across all sectors.
Another crucial factor to monitor is the Middle East conflict and crude oil prices, as energy costs bear a direct influence on inflation trajectories and could affect the monetary policy stance of the Federal Reserve.
Recently, Brent crude futures dipped below $100 per barrel amid market expectations regarding the U.S.-Iran negotiations and Saudi Arabia’s resumption of oil shipments through the East-West Pipeline, helping temper global supply anxieties.
Mr. Chaiyot views the easing of crude prices as a positive factor for investment sentiment, as it reduces energy cost risks and inflationary pressure. This follows earlier concerns that sustained high energy prices might increase uncertainty regarding the U.S. interest rate path.
Domestically, Mr. Chaiyot expects potential end-of-quarter portfolio rebalancing (window dressing) toward the end of September 2026 to lend support to the market, particularly for equities with solid fundamentals and positive earnings outlooks.
Concurrently, from late September into early October, market attention will increasingly turn toward third-quarter 2026 earnings expectations. Commercial banks, non-bank financial institutions, and energy companies will be the first sectors evaluated before attention extends to other industry groups.
Regarding domestic politics, KSS assesses that political developments may trigger periodic volatility in market sentiment. However, the securities firm does not currently regard politics as a primary driver for market strategy, though investors are advised to keep track of ongoing developments.
As for investment strategy, Mr. Chaiyot recommends selective stock picking focused on specific sectors and equities with individual positive drivers. KSS places top priority on the healthcare sector, highlighting BDMS as a top pick. KSS forecasts BDMS’s 3Q26 net profit could reach an all-time high of approximately THB 4.55 billion, boosted by seasonal rainy season patient volume and a surge in Middle Eastern patient arrivals. KSS considers BDMS suitable for gradual accumulation, maintaining a target price of THB 25.
Another sector identified as attractive by KSS is power plants, where declining crude oil prices and falling bond yields provide tailwinds for operating costs and equity valuations.
For top picks within utilities, KSS recommends GULF with a target price of THB 77, alongside GPSC with a target price of THB 61.