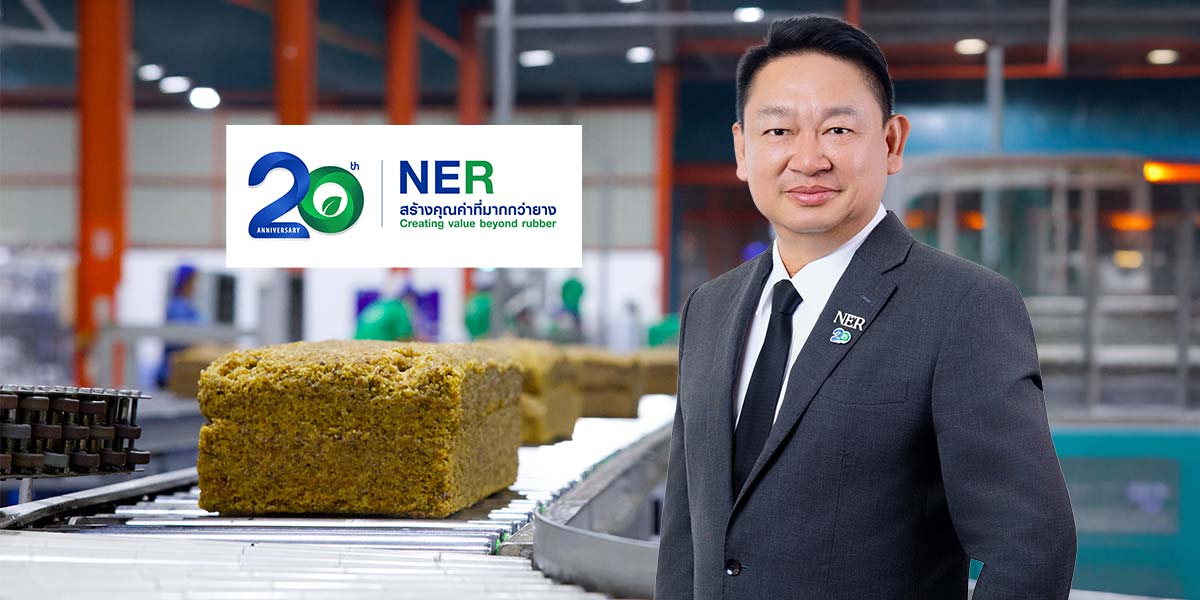
North East Rubber Public Company Limited (SET: NER) is expected to deliver stronger earnings in the third quarter of 2026, supported by rising rubber selling prices and resilient gross profit margins, despite supply constraints limiting sales volumes.
Brokerages forecast profit growth both year-on-year and quarter-on-quarter. However, their outlooks differ on fourth-quarter sales volumes and the potential impact of raw material shortages into 2027.
Yuanta Securities forecasts NER’s third-quarter core profit at THB 515 million, up 52% YoY and 15% QoQ. Net profit is estimated at THB 500 million after an anticipated net negative impact of approximately THB 15 million from foreign exchange losses and derivative gains.
The brokerage expects the average selling price to reach THB 72 per kilogram, rising 32% YoY and 22% QoQ. Sales volume is projected to remain broadly unchanged at 110,000 tonnes, while GPM should hold at 10%, compared with 9% a year earlier.
For the fourth quarter, Yuanta expects sales volume to remain at around 110,000 tonnes as supply stays constrained despite continued demand. Average selling prices could increase by at least 10% QoQ to THB 80 per kilogram, with GPM remaining near 10%.
Price-led revenue growth should limit increases in selling and administrative expenses, potentially making the fourth quarter NER’s strongest of the year. Profit could approach its previous quarterly record of THB 619 million, implying 9% upside to Yuanta’s 2026 earnings forecast.
If supply remains tight into 2027, Yuanta expects selling prices above THB 80 per kilogram, substantially exceeding its current THB 68 assumption. Although its 500,000-tonne sales forecast faces modest downside risk, the brokerage sees potential earnings upside of 8 – 10%.
Yuanta maintains a “Buy” recommendation with an end-2027 target price of THB 7.20. The firm expects a second-half 2026 dividend of THB 0.26 per share, representing a 5.6% yield.
Liberator Securities estimates 3Q26 net profit at THB 510 million, up 56% YoY and 17% QoQ. Revenue is forecast at THB 8,103 million, increasing 21% YoY and 13% QoQ.
The securities firm’s assumptions include a sales volume of 109,500 tonnes and an average selling price of THB 74 per kilogram. GPM is projected at 10.1%, improving from 8.9% a year earlier but remaining broadly stable sequentially as production costs also rise.
Unlike Yuanta, Liberator expects fourth-quarter sales volume to increase as rubber availability improves following the end of the tapping suspension season. Selling-price gains may be limited because orders were received during the third quarter.
Liberator retains its 2026 forecasts for core profit of THB 1,645 billion and net profit of THB 1,695 billion, while flagging potential upward revisions after results are released. The analyst maintains a “Buy” rating with a THB 5.50 target price, citing a 2026 price-to-earnings ratio of 4.4 times and an 8% dividend yield.
Daol Securities forecasts 3Q26 core profit—excluding FX losses—of THB 534 million, up 58% YoY and 19% QoQ.
However, the brokerage maintains a “Hold” call with a THB 5.00 target price, based on a 2027 price-to-earnings multiple of 5.2 times. Despite rubber prices rising 55% since the start of the year, Daol warns that drought effects could intensify and persist through at least the first half of 2027, potentially weakening sales volumes more than expected.